Opening a bank account shouldn't take longer than deciding to open one. But at many banks it still means filling out forms, uploading documents in another channel, waiting for validations, signing separately, or visiting a branch.
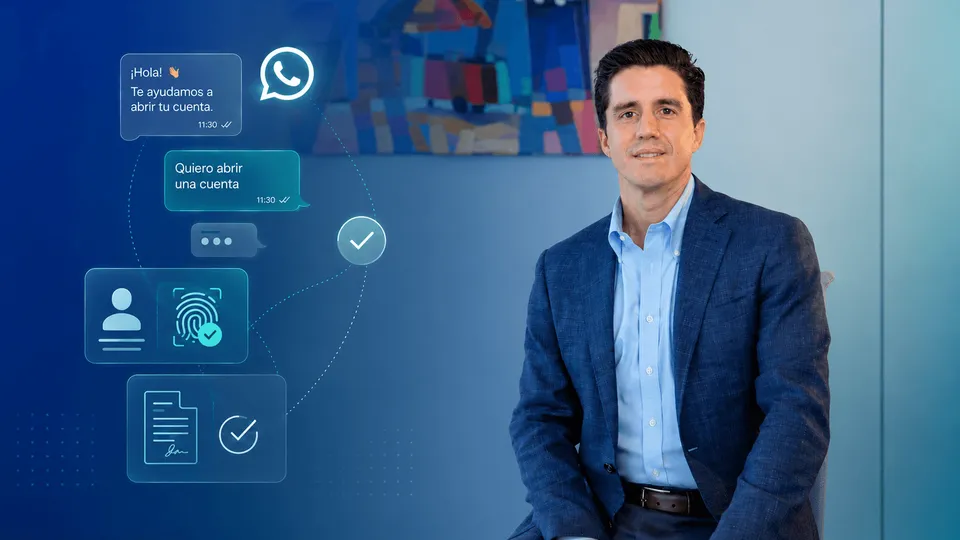
Banisi, one of Panama's leading banks, decided to add a channel its customers already use every day. With Jelou, it turned WhatsApp into a 100% digital account opening channel, with identity validation, biometrics, document upload, and e-signature inside the same chat, securely.
With that decision, it became the first bank in the region to enable account opening on that channel. The result was concrete: accounts opened in under 5 minutes, with no branch visits and a 146% increase in the opening rate compared with the previous web channel.
For Juan Emilio Lasso, executive chairman of Banisi, the decision came down to a simple idea:
“This is a true reflection that we listen to our customers. We know what matters to them, which is why we decided to bring the banking experience to where the customer is in their day-to-day.”
Why Banisi decided to add WhatsApp to bank onboarding
Banisi already had channels for opening accounts. Customers could do it at branches, in the app, or through direct private banking services. The decision was to add one more channel for those looking for a more immediate experience, available and close to their routine.
In banking, every extra step increases the likelihood of drop-off. A document uploaded in another environment, a selfie validated outside the flow, or a signature that arrives separately can turn a clear intention into an unfinished process.
WhatsApp solved an important part of that equation. It's a channel customers already understand, check several times a day, and use with no learning curve. For Banisi, bringing account opening into that environment meant reducing the time between a customer's interest and an open account.
What opening a bank account inside WhatsApp involves
Opening an account on WhatsApp isn't about sending a link or dropping a form into the chat. In Banisi's case, the user can start the application, provide their details, upload a photo of their ID, take a selfie for biometric validation, go through the necessary checks, and sign the contract electronically and securely.
It all happens in a single journey. Customers don't have to download another app, print documents, go to an office, or wait for an advisor to explain the next step through another channel. The conversation guides the process and reduces uncertainty at every stage.
For the bank, the benefit goes beyond the experience. Every step is traceable, measurable, and connected to the operation. That makes it possible to know where the customer moves forward, where they stall, when they need help, and how efficient the channel is compared to other acquisition points.
What the numbers show
The channel's growth confirmed that opening accounts on WhatsApp was a behavior customers were willing to adopt when the process took place in a familiar, guided environment available at any time.
The operation also gained scale. In 2025, the channel sustained thousands of account openings on WhatsApp and handled hundreds of thousands of cases, with a self-service rate of 64.6%. In other words:
Almost 2 out of 3 cases could be handled without human intervention.
In Q1 2026, the base kept growing. Self-service reached 73%, 8.4 percentage points above the previous year, while the channel kept growing in openings and cases handled.
For a bank, these figures aren't just about automation. They speak to acquisition, operational efficiency, and the ability to scale a conversational channel that doesn't stop at answering questions but completes banking processes.
The lesson for other banks
The Banisi case sends a clear signal to the financial industry: WhatsApp can be a banking acquisition channel, not just a support inbox. The difference lies in building it with transactional capability, security, and a connection to the processes the bank needs to run.
When identity validation, biometrics, e-signature, data, support, and traceability live in the same flow, the user doesn't feel like they're going through a procedure. They feel like the bank is taking steps away. And in banking, removing steps without losing control is a competitive advantage.
Banisi is already looking at other flows with Jelou. According to its CEO, the next step is to bring intelligent agents to more of the bank's processes, including customer service and credit approval.
The question for other banks is no longer whether an account can be opened on WhatsApp. The question is how many accounts they are failing to open because the customer still has to leave the channel where they were already ready to start.
Which process at your bank still forces customers to leave WhatsApp?
Account opening, credit, payments, collections, or e-signature can all live in a single conversational flow, with security, traceability, and less friction for the user.
Schedule a call with our team and let's see how it would look applied to your operation.